Room & board
Daily ward charges, meals and nursing care, up to the room class your plan entitles you to.

Hospitalisation, eligible medical expenses, coverage limits and the exact journey from admission to discharge explained without the fine-print fog.
Hospitalisation insurance is the core of any medical card. It steps in the moment you are admitted as an inpatient, and pays for medically necessary treatment while you are under a hospital's care.
Think of it as two promises. First, a ward promise: your room, nursing care and daily hospital charges are covered up to your entitlement. Second, a treatment promise: the doctors, surgeons, theatre, medication and investigations needed to make you well.
Most modern plans extend the cover before and after the admission too for the consultations, scans and follow-ups that surround a hospital stay.
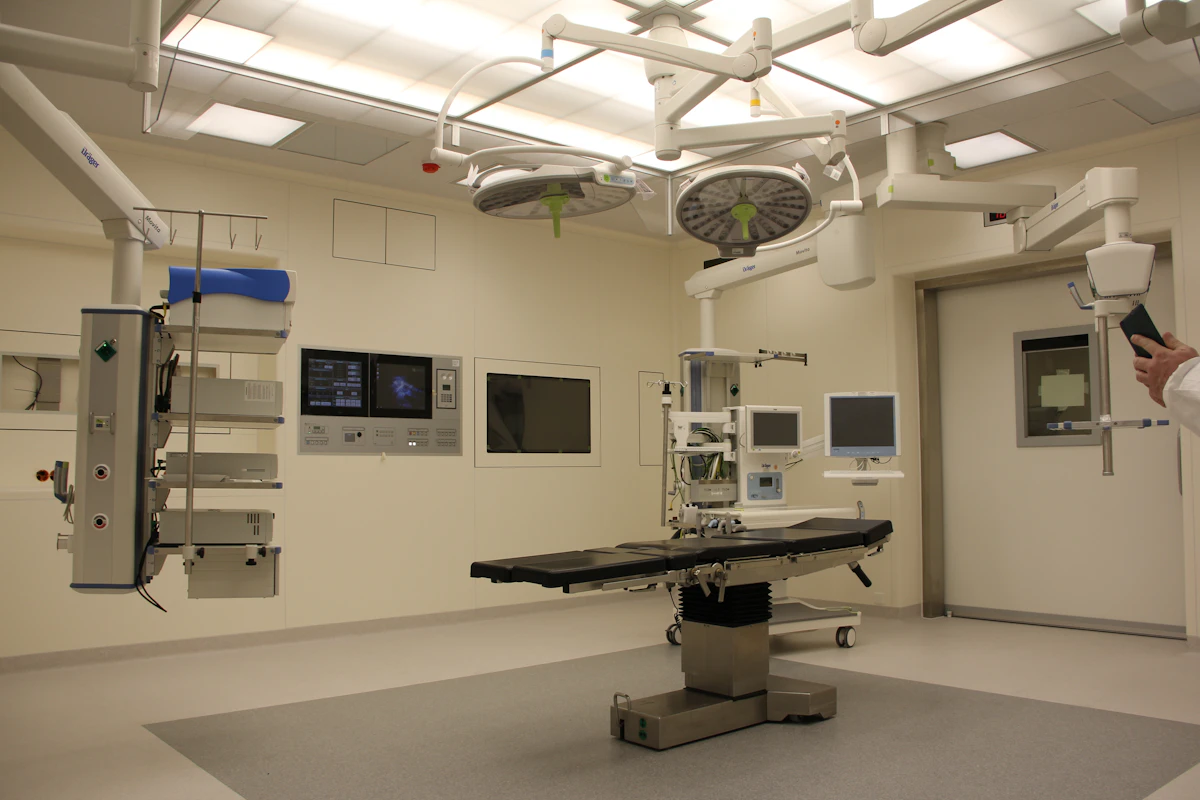
An "eligible medical expense" is a charge that is medically necessary, prescribed or performed by a licensed practitioner, and listed in your policy schedule. Here are the categories that make up the vast majority of hospital bills.
Daily ward charges, meals and nursing care, up to the room class your plan entitles you to.
Higher daily limits apply for ICU, CCU and high-dependency units and their specialised equipment.
Professional fees for the surgical team, usually within a reasonable-and-customary schedule.
Use of the operating suite, recovery areas and the equipment required during your procedure.
In-hospital prescriptions, drips and take-home medication related to your admission.
X-rays, ultrasound, CT, MRI and laboratory tests ordered to diagnose or monitor your condition.
Consultations and tests within a defined window before admission and after discharge.
Procedures that don't need an overnight stay, such as endoscopy or minor operations.
If a treatment is medically necessary, ordered by a licensed doctor and listed in your schedule, it is very likely eligible. If it is elective, cosmetic or unrelated to a covered condition, it usually isn't. When in doubt, our advisers will check before you commit not after.
Limits are the guardrails of your policy. Reading them correctly is the difference between "fully covered" and a very expensive surprise.
The maximum the insurer will pay for all claims within one policy year. It refreshes every year but a serious illness can consume an entire year's limit in one admission.
The total the insurer pays across the life of the policy. Newer plans often remove this cap entirely a major advantage for chronic conditions.
Your daily room class (e.g. RM 350/day). Choose a more expensive room and you usually pay the difference yourself, plus a proportion of the bill.
Some plans ask you to share a small portion of each bill a fixed deductible and/or a percentage co-payment. Lower sharing means higher premiums.
New policies often have waiting periods commonly 30 days for illness, longer for specific conditions such as maternity or certain procedures.
A sub-cap on one condition (e.g. cancer treatment per year). Always check the sub-limits, not just the headline annual figure.
| What it decides | Lower-cost plan | Balanced plan Popular | Comprehensive plan |
|---|---|---|---|
| Annual limit | RM 100,000 | RM 1,000,000 | Unlimited |
| Room & board | RM 150/day | RM 350/day | Any room class |
| ICU daily limit | RM 300/day | RM 700/day | As charged |
| Pre / post-hospitalisation | 30 / 60 days | 60 / 90 days | 90 / 180 days |
| Overseas emergency | Reimbursement | Worldwide assistance | |
| Typical fit | Students, first jobs | Families, couples | Executives, frequent travel |
Scroll the table horizontally to compare all columns.
A medical card is your membership to a network of panel hospitals and specialists. Here is exactly what happens when you use it and the two ways a claim can be settled.
Call your adviser or the insurer's hotline to confirm which panel hospital suits your condition and confirm your room entitlement. We'll tell you exactly which ward class keeps you fully covered.
The admission counter scans your card, verifies your active status and registers you under the insurer's panel. No deposit is required for covered treatment within your entitlement.
The hospital sends the treatment plan to the insurer, which issues a guarantee of payment. This is the approval that confirms the covered charges will be settled directly.
Your room, surgery, medication and investigations are charged to the insurer up to your limits. You focus entirely on getting better.
You sign the discharge form. Only non-covered items (a room upgrade, excluded items, co-payment) are payable by you at the counter.
If you were treated at a non-panel hospital, you pay first and submit the bills. Our claim concierge prepares and tracks the reimbursement until it's paid.
The insurer pays the hospital directly for covered charges. You present your card, sign, and walk out no upfront payment, no waiting for reimbursement.
At non-panel hospitals, or overseas, you settle the bill yourself and claim it back. Keep every receipt, discharge summary and medical report we'll organise the rest.
Emergency admissions don't wait for paperwork. Go to the nearest panel hospital's A&E, present your card on arrival, and notify your adviser the same day. Insurers accept emergency notifications after the fact the golden rule is simply to tell us early.
Every policy has exclusions. Knowing them upfront prevents disappointment at the worst possible moment.
The good news: many exclusions can be managed. Declaring conditions honestly at the start, adding the right riders, and choosing adequate limits closes most of the gaps.
Routine dental scaling, fillings, spectacles and contact lenses are normally excluded from a standard medical card. Some insurers offer optional outpatient riders that cover them up to a small annual sub-limit ask us to quote one alongside your main plan.
Insurers assess known conditions during underwriting. Depending on the condition, cover may be offered with an exclusion, a loading (higher premium), or deferred for a period. Never hide a condition a non-disclosure can void a future claim entirely.
Employer plans end when you leave. A personal medical card travels with you regardless of employment which is why we always recommend building your own cover alongside, or instead of, relying on a group plan.
Yes. Medical premiums are typically age-banded and review periodically, reflecting medical inflation. Because the bands rise with age, locking in cover earlier usually means paying less over a lifetime of coverage.
Notify the insurer's emergency assistance line as soon as possible, keep every original bill and medical report, and settle the hospital yourself. On return, submit the claim we help compile the documents and follow it through to payment.
Twenty minutes with an adviser will tell you more than twenty hours of fine print. Free, and with no obligation to proceed.